AGED DEBT ACTION PLAN
Reduce aged debt with a clear 30-day action plan
For SMEs with several overdue invoices and no clear order of action. We review your aged debtor position, prioritise the accounts and give you a practical 30-day plan, with the wording and templates needed to act.
Someone hasn’t paid? Start here.
Download the overdue invoice checklist. What to check, what to send, when to call and when to escalate.
Aged debt reduction in under three months
WHERE DEBT STALLS
Aged debt grows when the next step isn’t clear
Aged debt is money sitting unpaid beyond the agreed payment date. Once several accounts are overdue at different stages, another generic reminder isn’t enough.
You need to know which accounts can be resolved quickly, which have a genuine dispute, which need firmer chasing and which are ready to escalate.
The Aged debt action plan turns that backlog into a clear priority order, with a defined next action for each account.
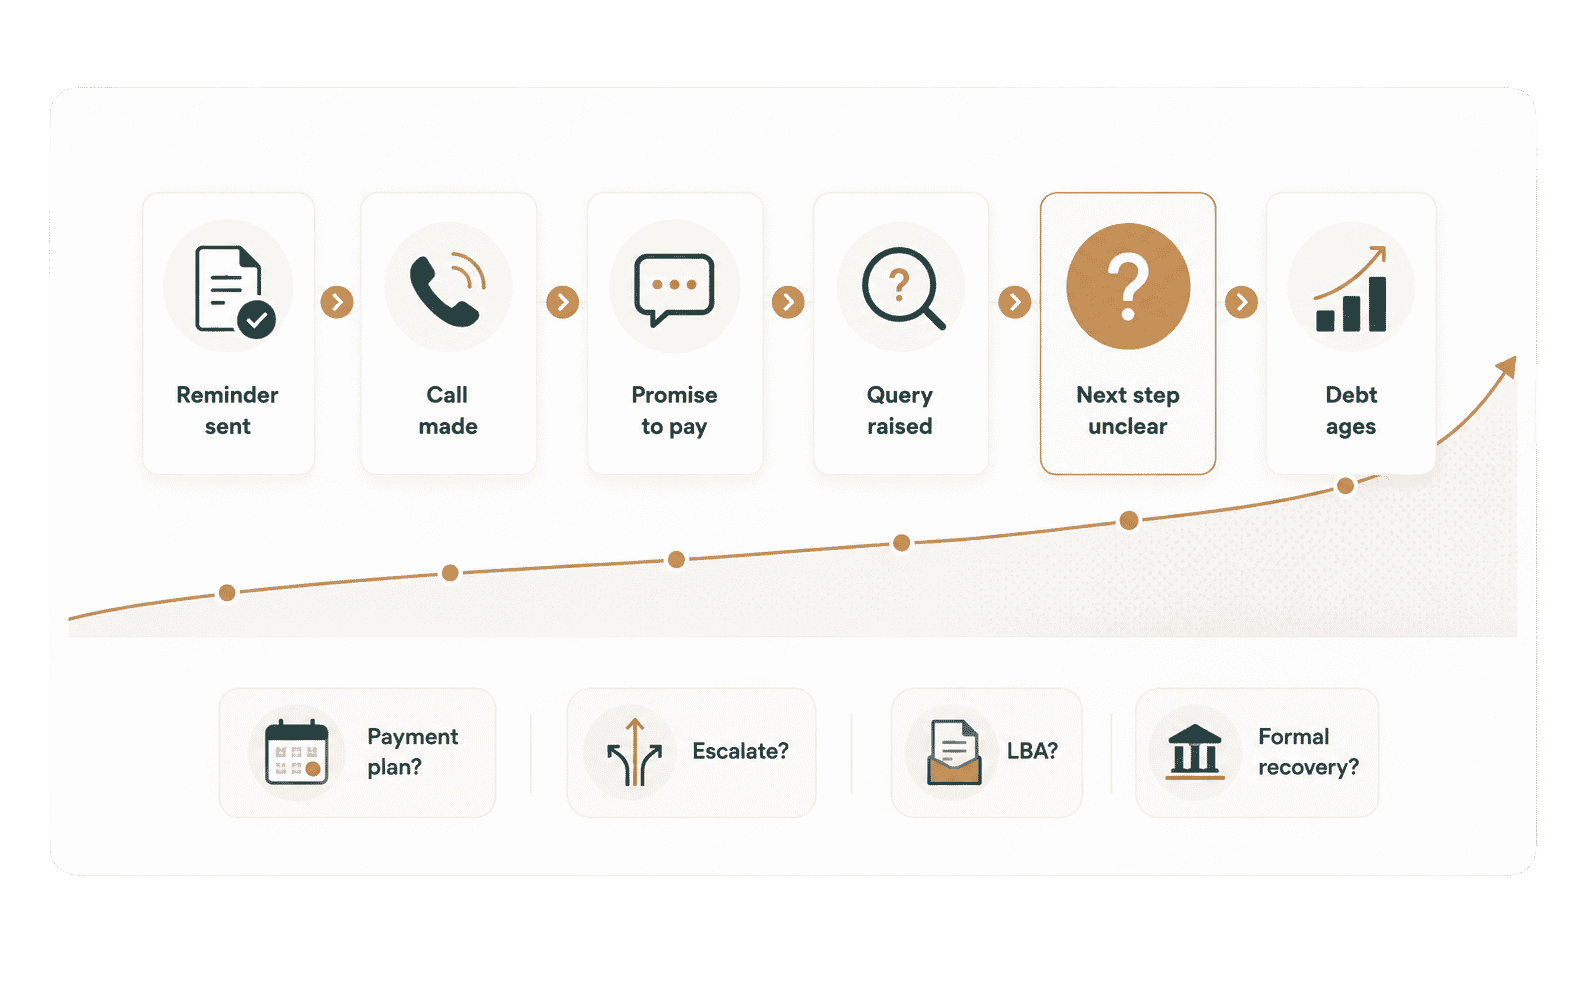
Customers keep promising payment
They sound reasonable. The money still doesn’t land.
Your aged debtor report keeps growing
The numbers are there. The next steps aren’t.
Disputes appear too late
The invoice was ignored until payment became unavoidable.
Chasing is scattered
Emails are sent, calls are made, but no one owns the route through.
Payment plans are too loose
A customer offers instalments and the business accepts without enough structure.
No one knows when
to escalate
The business stays polite for too long, then reacts too late.
Get every overdue account ready for the right next action
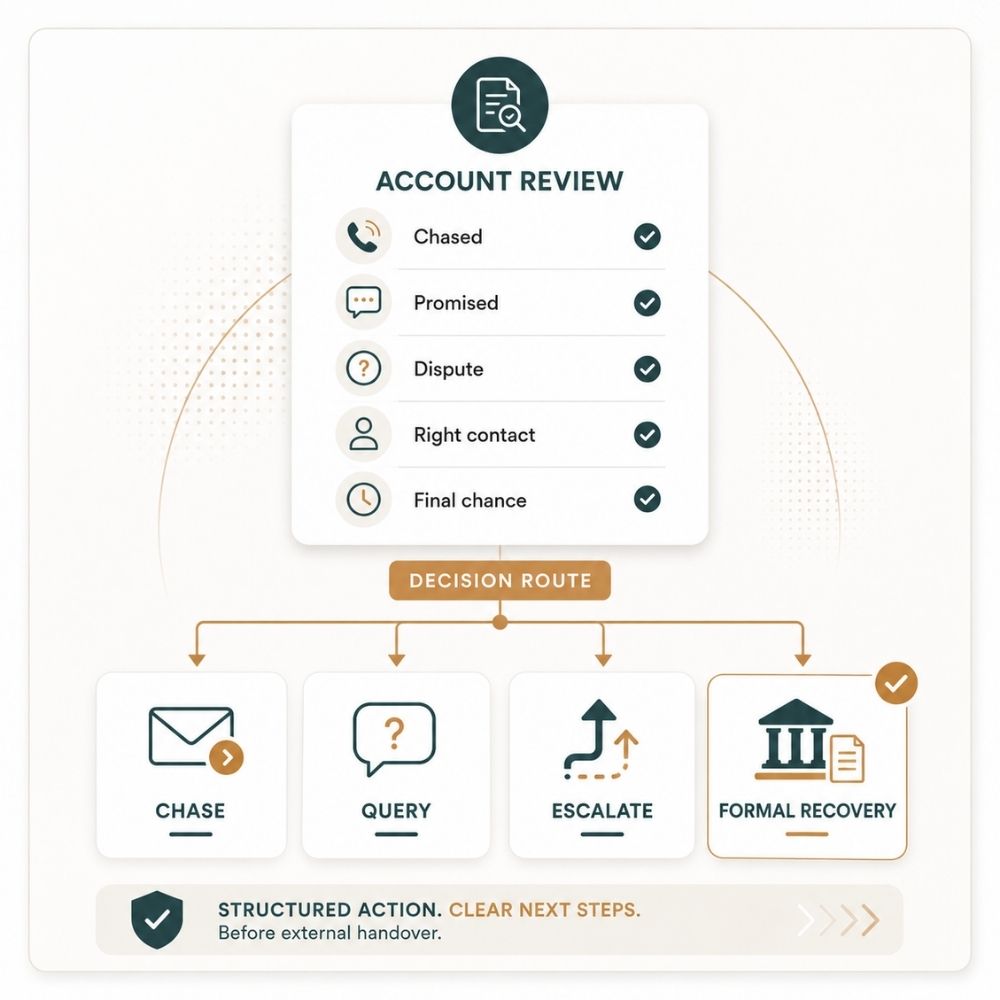
Before an overdue account is escalated, you need a clear picture of what’s happened so far: who’s been contacted, what’s been promised, whether there’s a dispute, which deadlines have passed and whether the customer has had a final opportunity to pay.
This is where accounts often stall. Chasing carries on, promises slip and nobody is quite sure when to change approach.
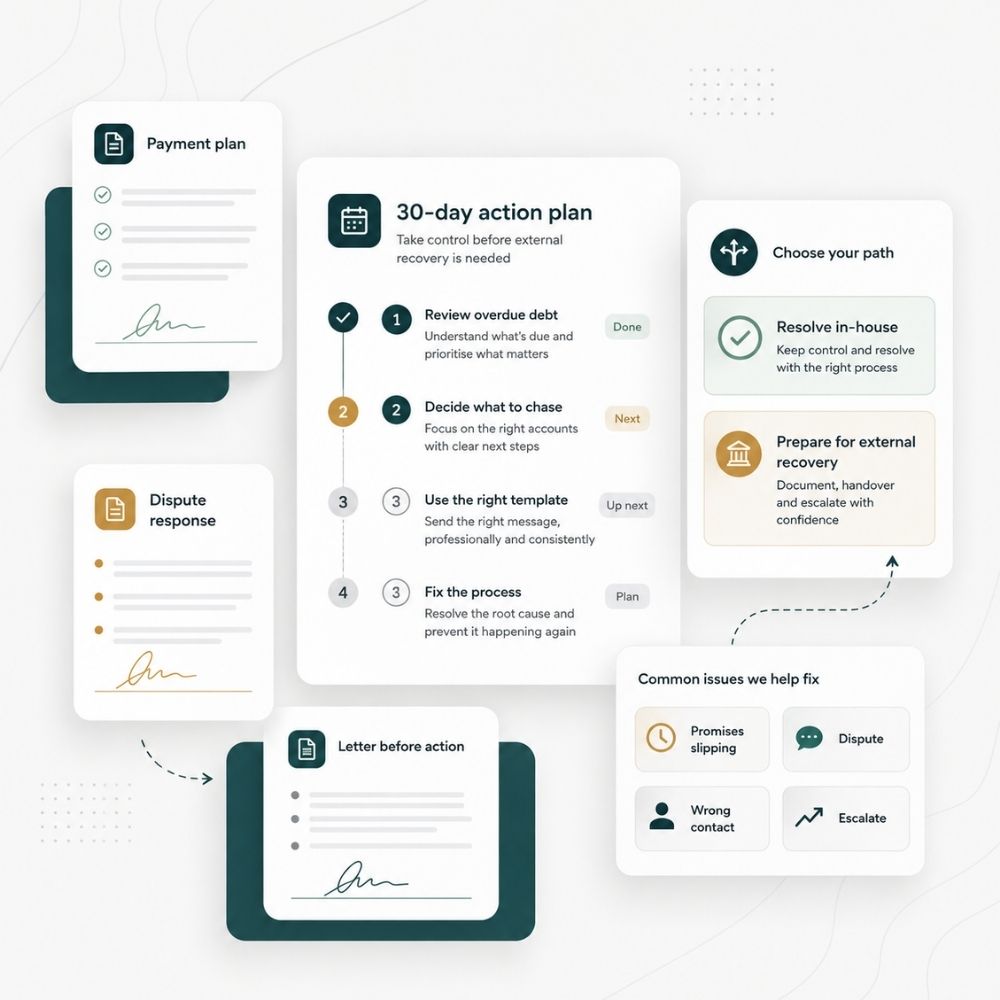
The Aged debt action plan & templates gives you that structure. We review the account, set the next action and give you the wording to chase, query, agree a payment plan, escalate or prepare the debt for formal recovery.
EXPERIENCE BEHIND THE PLAN
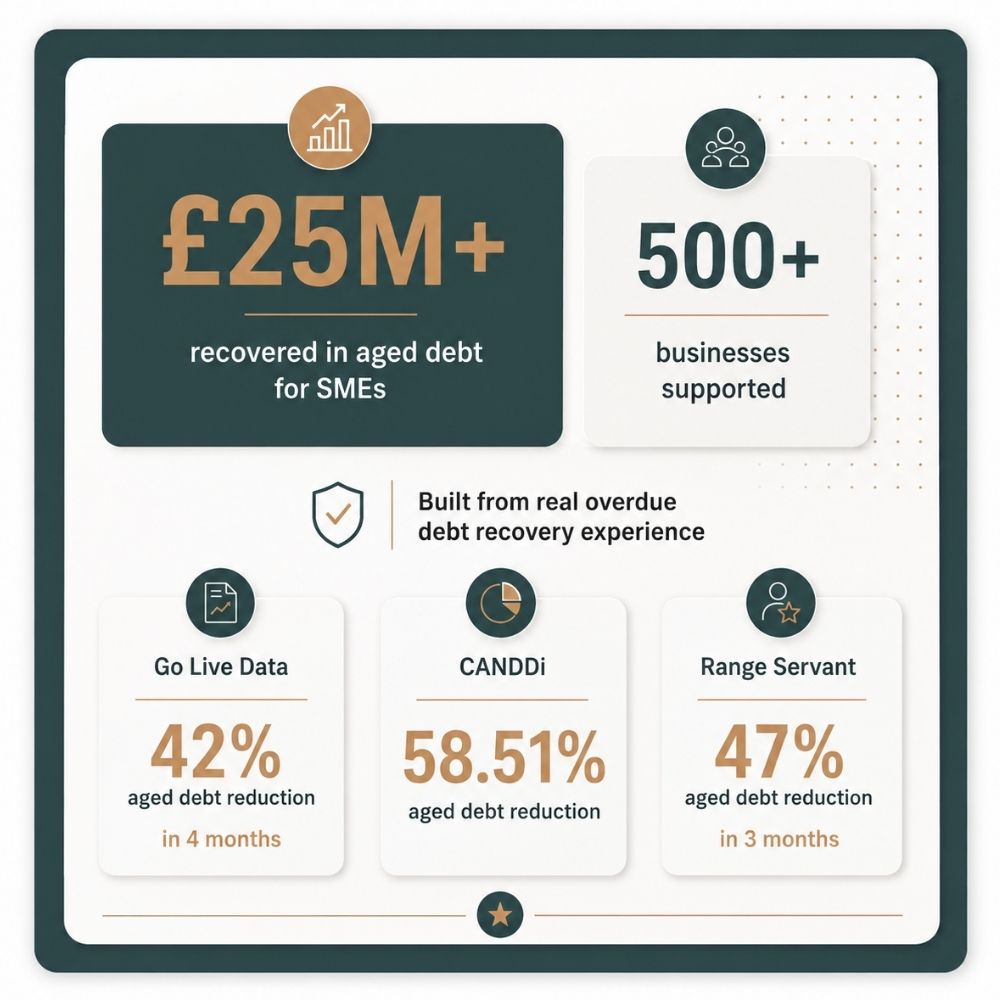
Built from £25m+ of debt recovery experience
Before Collect Wise, Paula Bolton founded, scaled and sold FJCM, supporting more than 500 businesses with overdue debt and collections and recovering more than £25m for clients.
The same problems appeared repeatedly: promises weren’t followed up, disputes sat unresolved, chasing became inconsistent and escalation happened too late. That experience now sits behind every Collect Wise aged debt action plan.
The scale of late payment
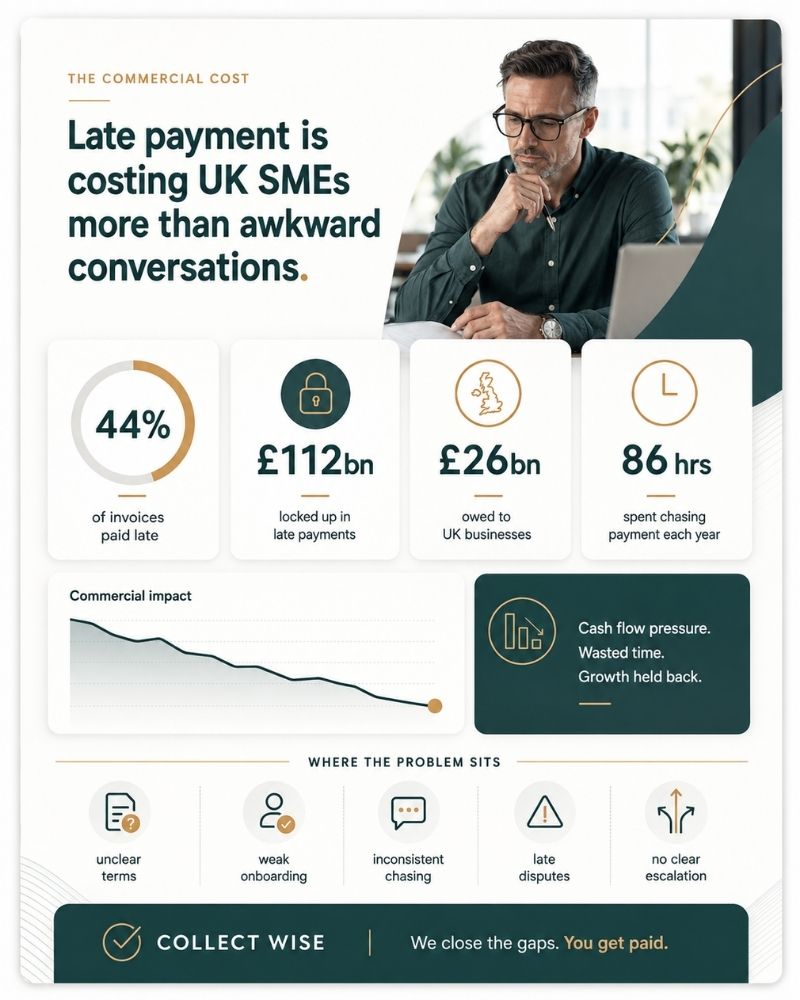
£26bn is sitting unpaid to UK businesses
Late payment is still one of the biggest payment problems facing small and medium-sized businesses.
Recent research found that 44% of invoices were paid late, with £112bn locked up in late payments. Government-backed research also estimates that UK businesses are owed £26bn in late payments at any given time, with affected businesses spending an average of 86 hours a year chasing payment.
The issue usually sits in the gaps: unclear terms, weak onboarding, inconsistent chasing, late disputes and no clear escalation point.
That’s the bit Collect Wise helps with.
We help SMEs improve the credit control process, make better collections decisions and deal with overdue invoices in a way that is firm, clear and commercially sensible.
Who this is for
Is an aged debt action plan right for your business?
This package is a good fit if:
- Your aged debtor report is growing
- Customers keep promising payment but nothing lands
- You have several overdue invoices and no clear priority order
- Some invoices may be disputed
- Chasing is happening, but not systematically
- Payment plans are being agreed too loosely
- You're unsure which accounts need firmer action or how to use Letter Before Action wording
This is designed for businesses with several overdue accounts or a growing aged debtor position.
If you only have one straightforward overdue invoice, start with our overdue invoice checklist.
If the underlying problem is that late payment keeps repeating, our credit control consultancy may be the better starting point.
WHAT’S INCLUDED
What your aged debt review and action plan covers
We review the aged debtor position, group accounts by risk and urgency, then give each account a clear next action.
Aged debt review
Debtor segmentation
Easy wins, slow payers, disputes, higher-risk accounts and escalation cases
Priority chasing list
Which accounts need attention first and why
Recommended next action by customer
Chase, call, query, payment plan, escalate or prepare for formal recovery
30-day collection action plan
A structured route through the ledger
Chasing wording and templates
Reminders, firmer follow-up, broken promises and final warnings
Payment plan and dispute wording
Clearer arrangements and responses to overdue queries
Dispute response wording
Letter Before Action template
Sets out the debt, deadline and next step properly.
Escalation guidance
When normal chasing should move towards interest, final demand, Letter Before Action or formal recovery
Recovery handover guidance
What to prepare if an account needs a debt collector or solicitor
Our Process
How the aged debt action plan works
1
Send the information
Your aged debtor report plus a short set of questions about chasing, disputes and payment history.
2
We review the debt
We identify what needs chasing, querying or escalating and which accounts carry greater risk.
3
You get the action plan
A practical 30-day collection plan with priorities, recommended next actions and supporting wording.
4
You know what happens next
Every reviewed account has a clearer route rather than another round of open-ended chasing.
ACTION PLAN OR DEBT RECOVERY?
This isn’t a debt collection service
The Aged debt action plan helps you understand what can still be resolved through your own credit control process, what needs firmer escalation and which accounts may now be ready for external recovery.
If an account has reached that point, we’ll make that clear and help you understand what information should be ready for the next stage.
RESULTS
Aged debt case study: from growing debt to zero outstanding
Range Servant had persistent late payments, growing aged debt and too much time being spent chasing customers.
After strengthening the credit control process, introducing proactive chasing and improving account setup and monitoring, aged debt fell 47% in three months. By January 2024, it was down to zero.
Aged debt reduction – Go Live Data · 4 months
Aged debt reduction –
CANDDi
Aged debt outstanding –
Range Servant · January 2024
47% Aged Debt Reduction in three months
FREE PRACTICAL RESOURCE
Only dealing with one overdue invoice?
Download the free overdue invoice checklist for a simple step-by-step guide covering what to check, what to send, when to call and when to escalate.
Things You Need to know
Frequently Asked Questions
What is aged debt?
Aged debt is money owed on invoices that have passed their agreed payment date and remain unpaid. An aged debtor report usually groups outstanding balances by how long they have been overdue, helping a business see where payment risk is increasing.
How can a business reduce aged debt?
Reducing aged debt starts by understanding which accounts need attention first. That means separating straightforward late payments from disputes, broken promises, payment-plan cases and accounts that may need escalation, then giving each one a clear next action.
What does an aged debt review include?
Collect Wise reviews your aged debtor position, the age and history of outstanding accounts, previous chasing, payment promises, disputes and escalation status. We then prioritise the accounts and provide a practical 30-day action plan.
Is this the same as using a debt collection agency?
No. The Aged debt action plan is designed to help you decide what can still be resolved through your own credit control process and what needs escalation. If an account appears ready for external recovery, we’ll identify that as part of the review.
What happens if some invoices are disputed?
Disputed invoices are identified separately so they aren’t treated like straightforward late payments. The action plan considers what information or response is needed to move the dispute towards resolution before further collection action is taken.
What if our aged debt keeps building again?
That usually indicates a wider credit control process issue. Our credit control consultancy reviews payment terms, onboarding, invoicing, chasing, disputes and escalation to identify what is allowing late payment to repeat.
READY TO GET CLEAR ON WHAT’S OVERDUE?
Get a clear plan for your aged debt
Tell us what’s currently sitting overdue and we’ll discuss whether the Aged debt action plan is the right starting point.